Blog
Discover everything
Blockrise has to offer.

Getting off zero: from passive to managed exposure
A passive bitcoin holding transfers the full volatility of bitcoin into the portfolio. Blockrise Research examined what changes when that exposure is managed by rule instead, over the period from January 2017 to June 2026.
The question is not whether bitcoin has performed
Institutional mandates are written around risk budgets, drawdown limits and reporting obligations. The return history of bitcoin is well documented. For many allocators the obstacle is not that history but the path to it: bitcoin moves in larger swings than the holdings those mandates were designed for.
The first article in this series showed that a modest passive bitcoin allocation increased both returns and risk-adjusted returns in a traditional 60/40 portfolio. That analysis assumed a passive holding with periodic rebalancing. This second article asks the follow-up question: what changes when the position is managed rather than held?
Aegis is an actively managed bitcoin strategy based on Blockrise’s bitcoin cost price model, which approximates the cost of producing one bitcoin, adjusted for mining capital expenditure and changes in network activity. The strategy rebalances monthly to the weight that this valuation indicates. Where the market price sits below the cost price, it increases the bitcoin position. Where the market price sits above it, it decreases the position. The allocation can range from 0% to 100%, and a safety trigger moves the portfolio fully to cash when overvaluation passes a defined threshold.
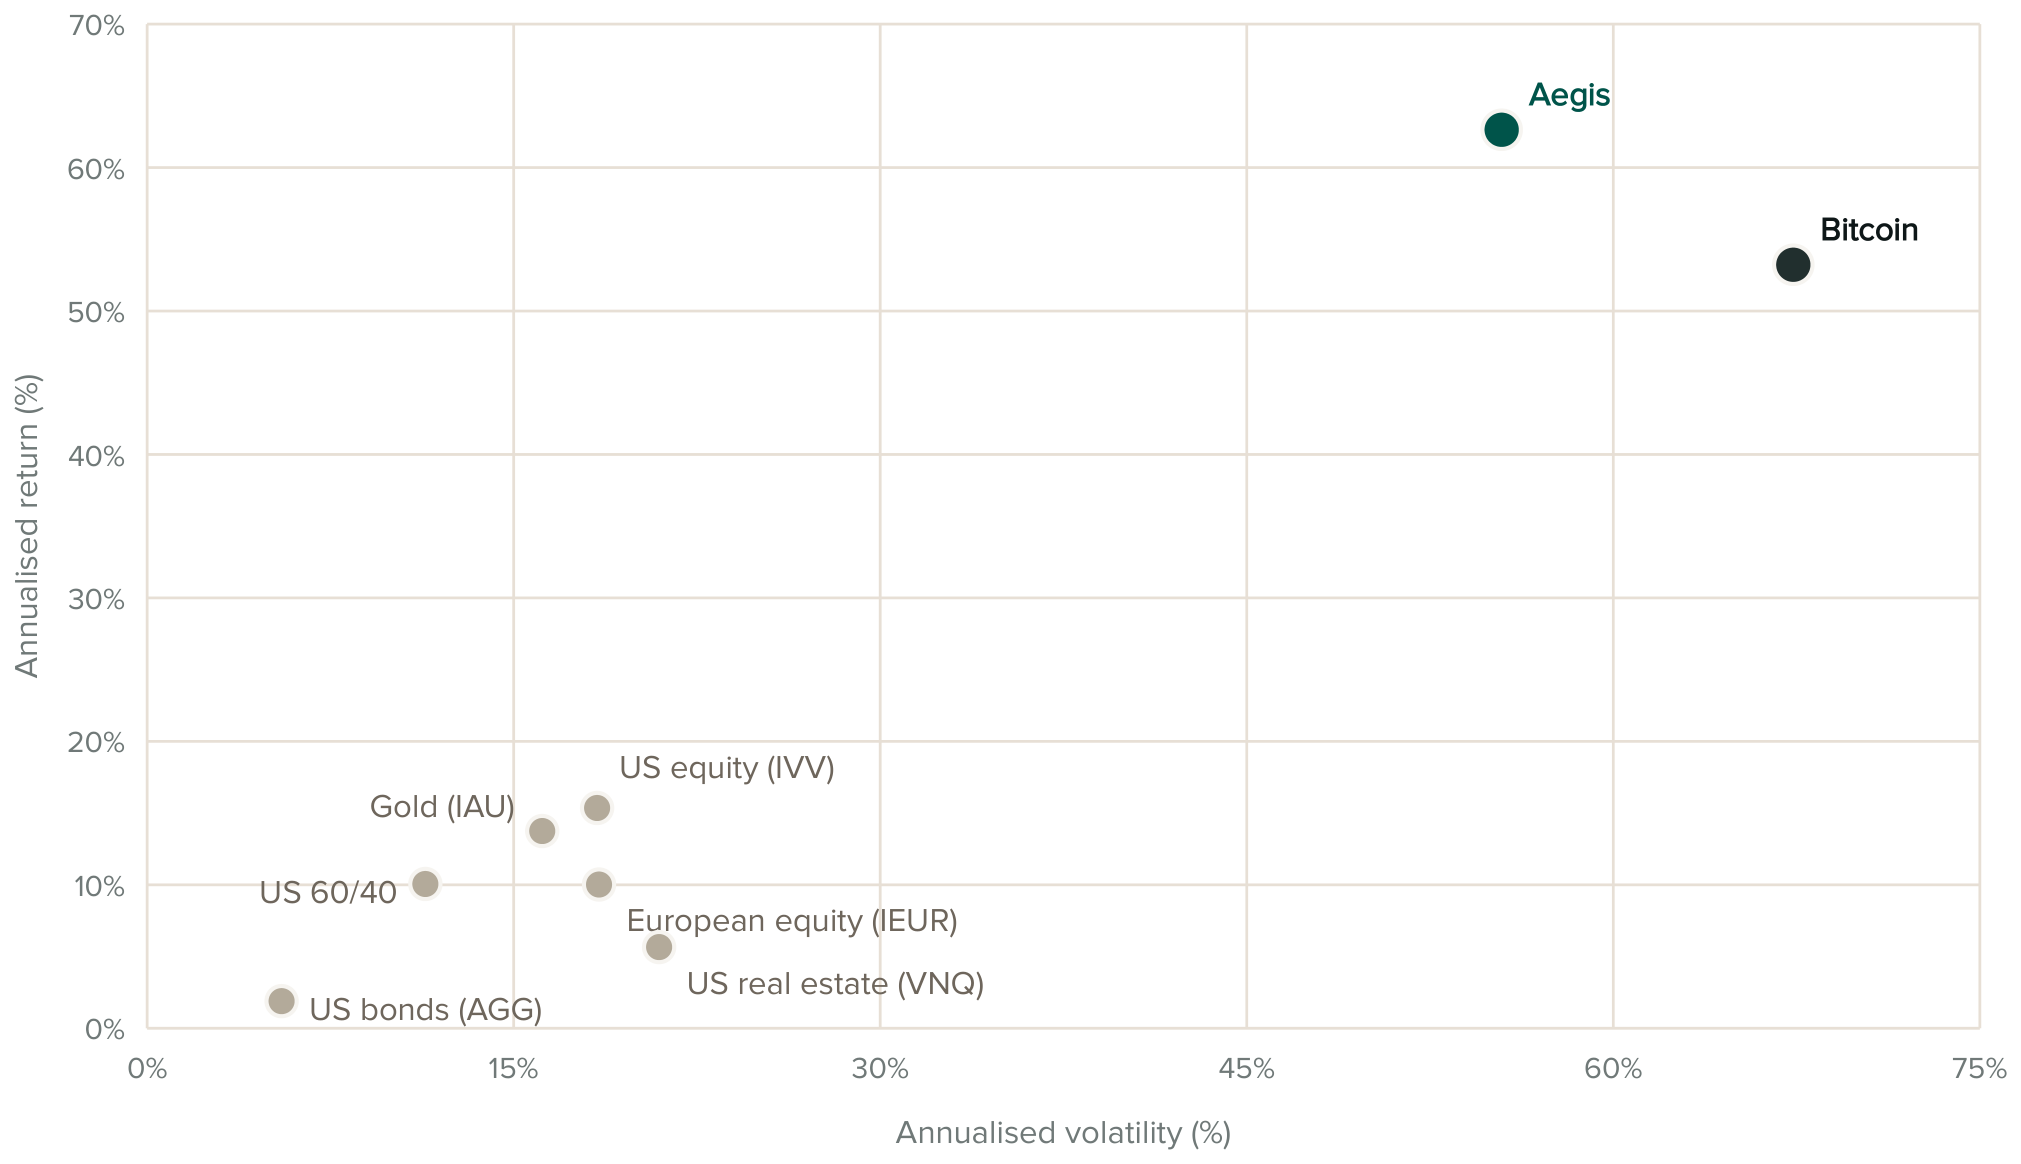
Over the full study period Aegis returned 62.64% a year, against 53.23% for a direct bitcoin holding, at an annualised volatility of 55.43% against 67.37%. The Sharpe ratio was 1.11 against 0.94 and the Sortino ratio 1.70 against 1.41. All Aegis figures are net of costs: a 1.82% annual management fee accrued daily, and 0.30% of traded notional at each rebalance. These are backtested results over a closed period. Past performance of crypto assets does not guarantee future returns.
Correlation is low, but not under all conditions
Diversification only earns its place if it holds when the portfolio needs it. Over the full period the correlation of Aegis daily returns to the five conventional holdings in the study ranged from 0.10 to 0.24, all of it inside the weak band below 0.30.
An average across nine years says little about the days that do the damage, because ordinary days outnumber them. Correlation was therefore measured over the stressed months alone: the 60 trading days on and after each of eight macroeconomic, geopolitical or systemic shocks, together 480 of the 2,384 trading days in the period, or 20.1%. Across those months the correlation of Aegis rose to a range of 0.18 to 0.46. Independence weakens when markets fall. Over the same months, US equity, European equity and US real estate correlated 0.80 to 0.88 with one another.
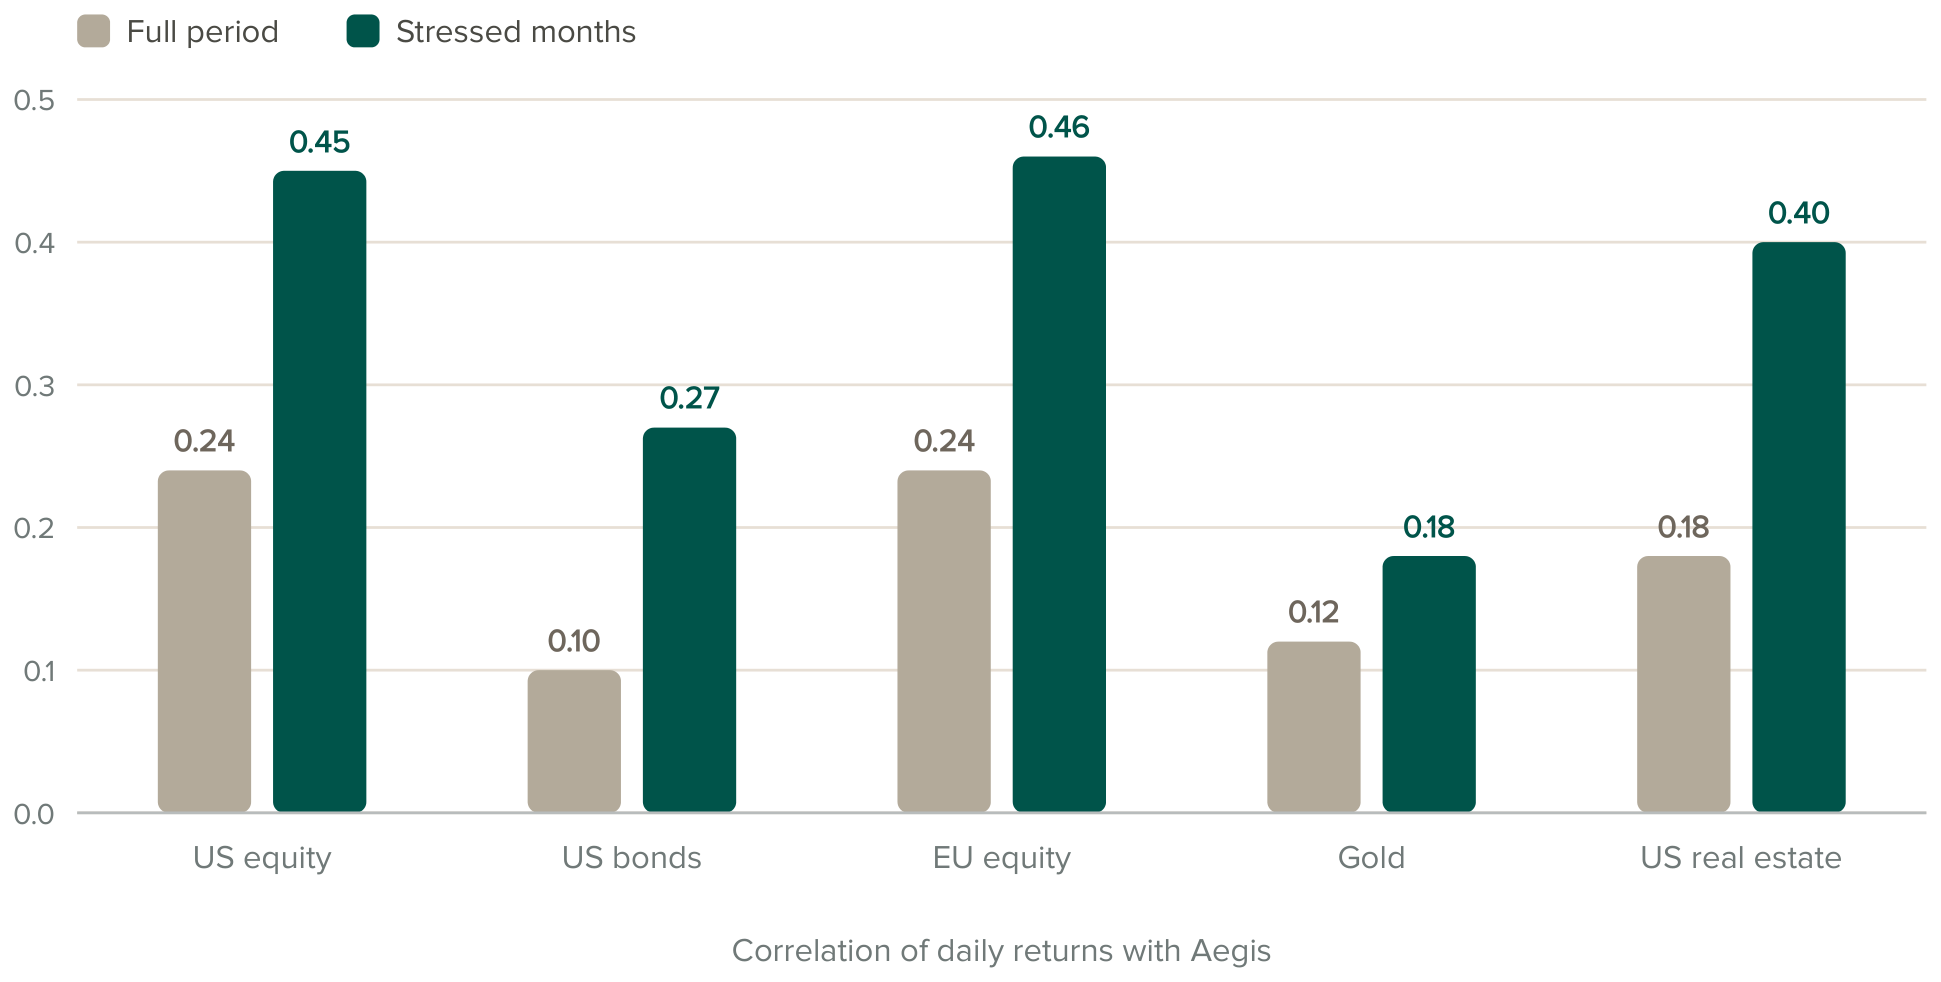
Taking the eight events individually, Aegis was positive 60 days after onset in six of the eight. Its average gain across those six was 17.3%, against an average loss of 7.0% across the two negative events. Both equity indices show the reverse: US equity gained 9.3% on average and lost 11.3%, European equity gained 9.0% and lost 16.5%. Aegis carries roughly three times the volatility of US equity, but across these events that volatility was skewed to the upside.
What the strategy does inside a portfolio
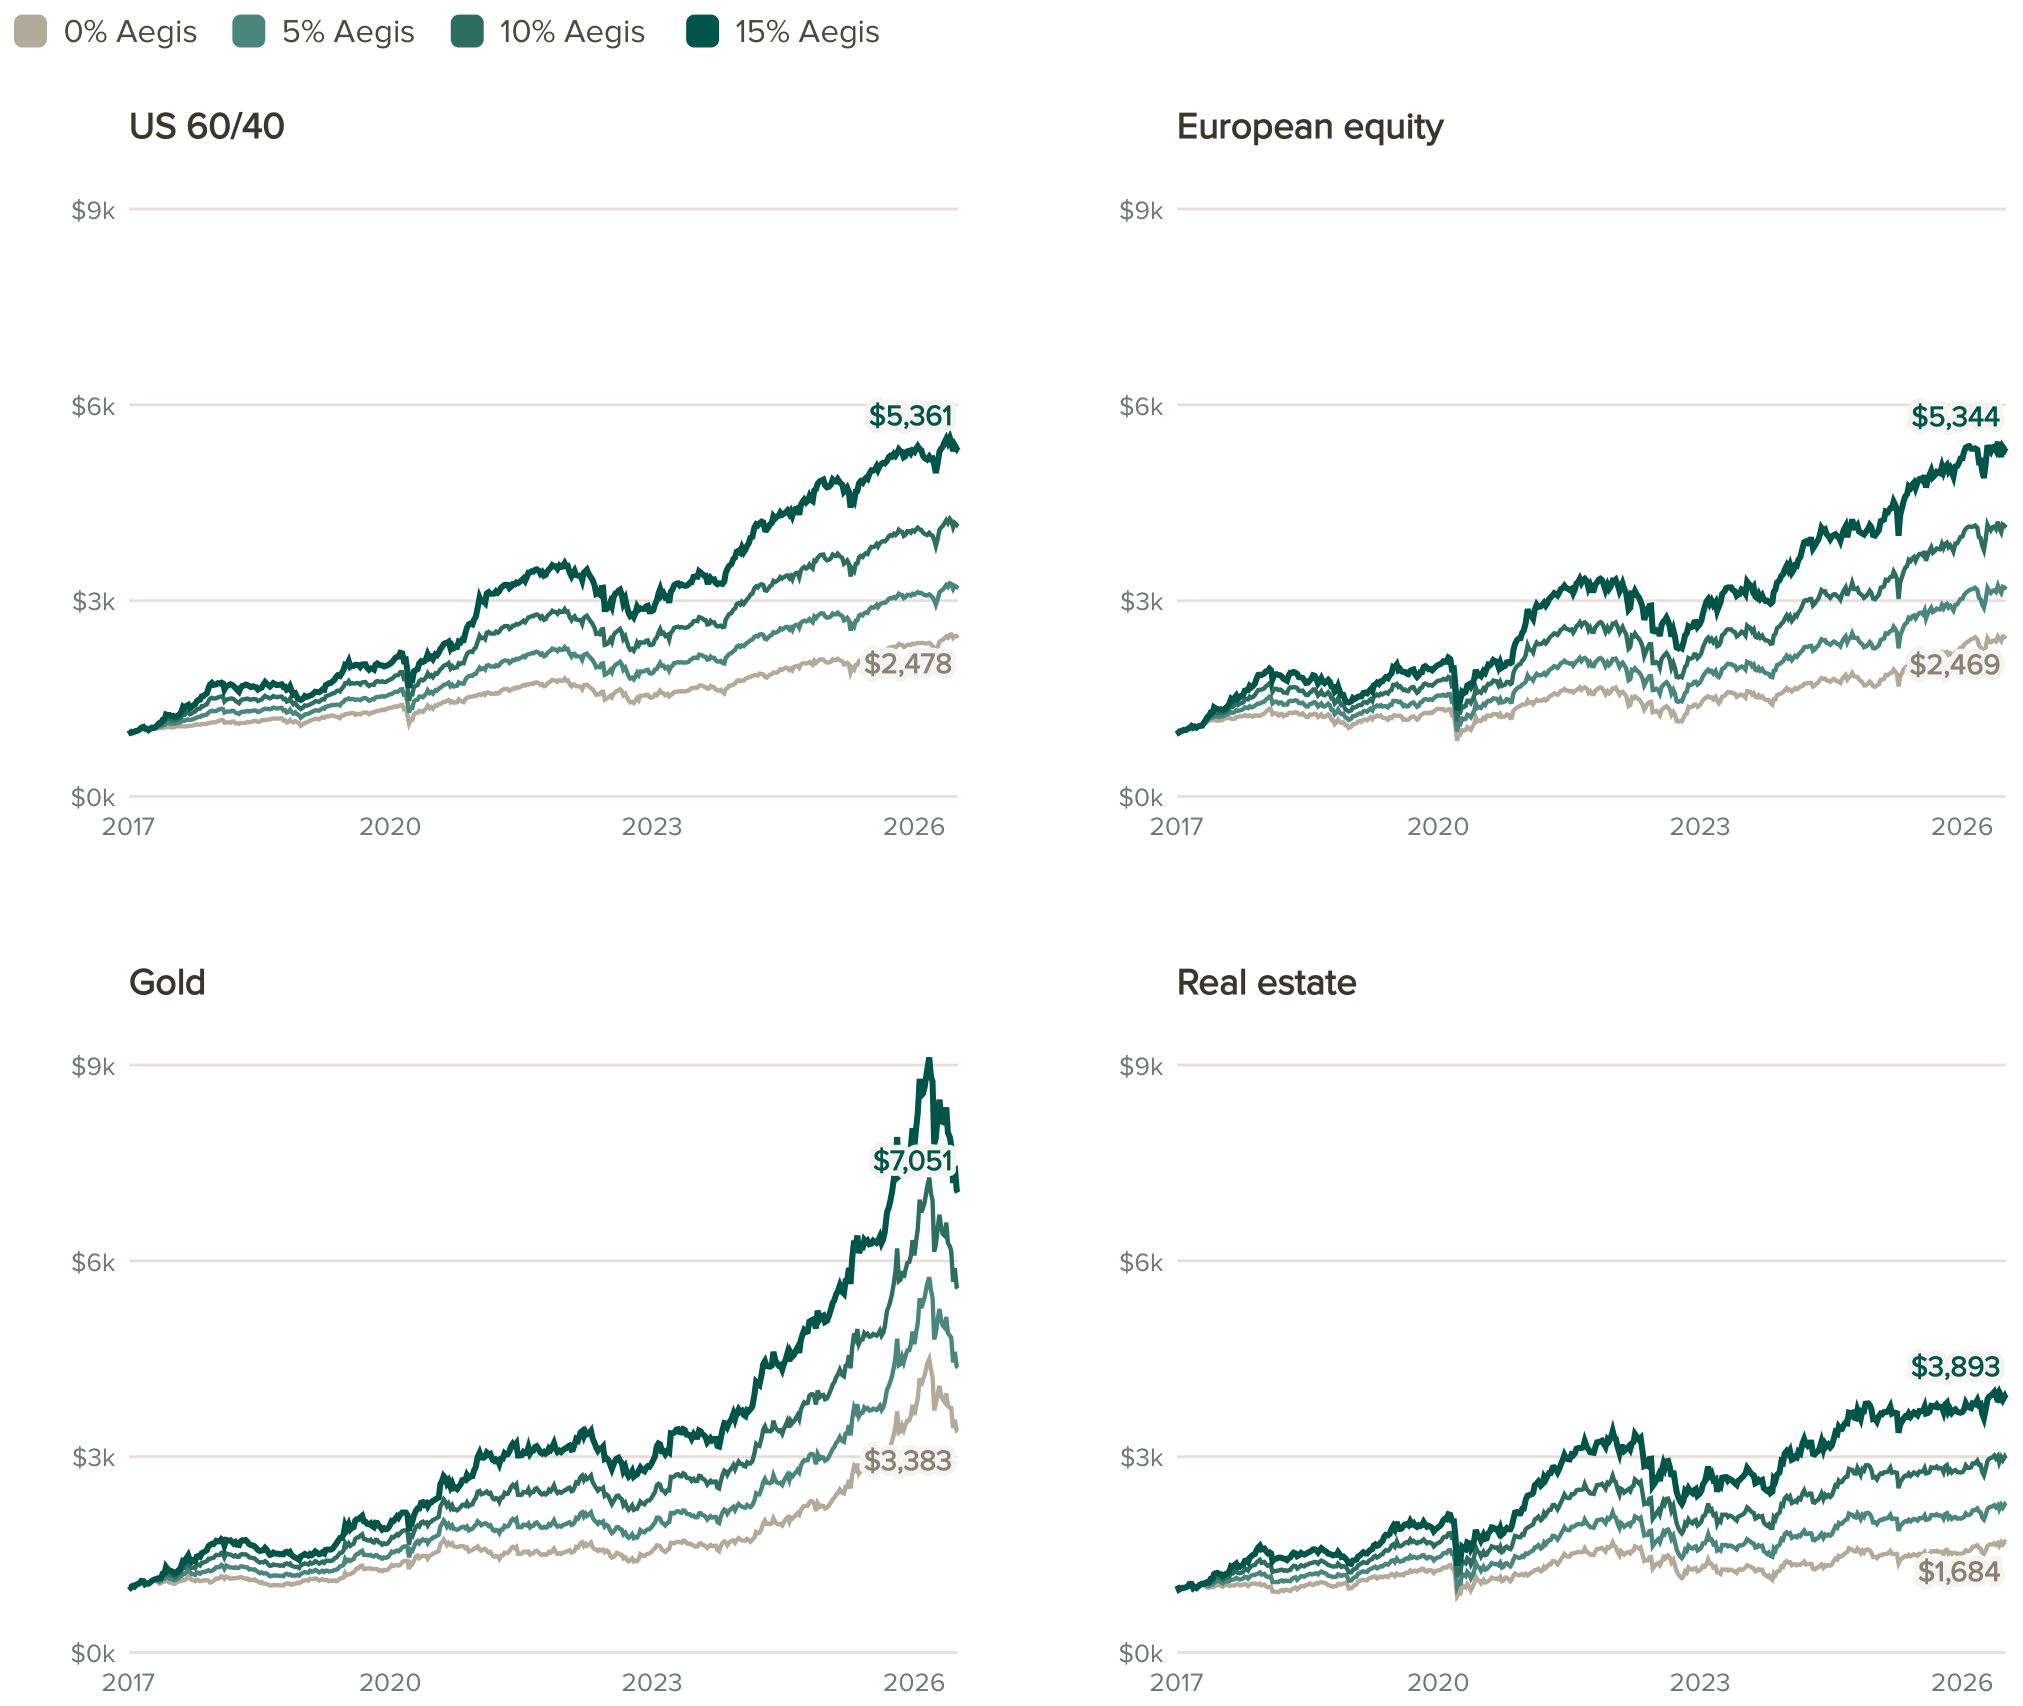
Aegis was then added to four base allocations: US 60/40, European equity, gold and US real estate. At allocations from 0% to 30%, both the annualised return and the Sharpe ratio increased at every step, for every base allocation. The direction was the same everywhere. The size of the effect was not.
The marginal benefit does fade. Extended across the full 0% to 100% range, the Sharpe gain per additional percentage point of Aegis falls below 0.01 at an allocation of 18% for US 60/40, 21% for gold, 27% for European equity and 34% for US real estate. No allocation was simultaneously optimal on risk-adjusted return and on the depth of the loss.
Translated into money: an illustrative $1,000 invested entirely in US 60/40 on 3 January 2017 ended at $2,478. The same portfolio with a 15% Aegis allocation ended at $5,361. Gold alone ended at $3,383, and at $7,051 with 15% Aegis.
The figures that show the other side
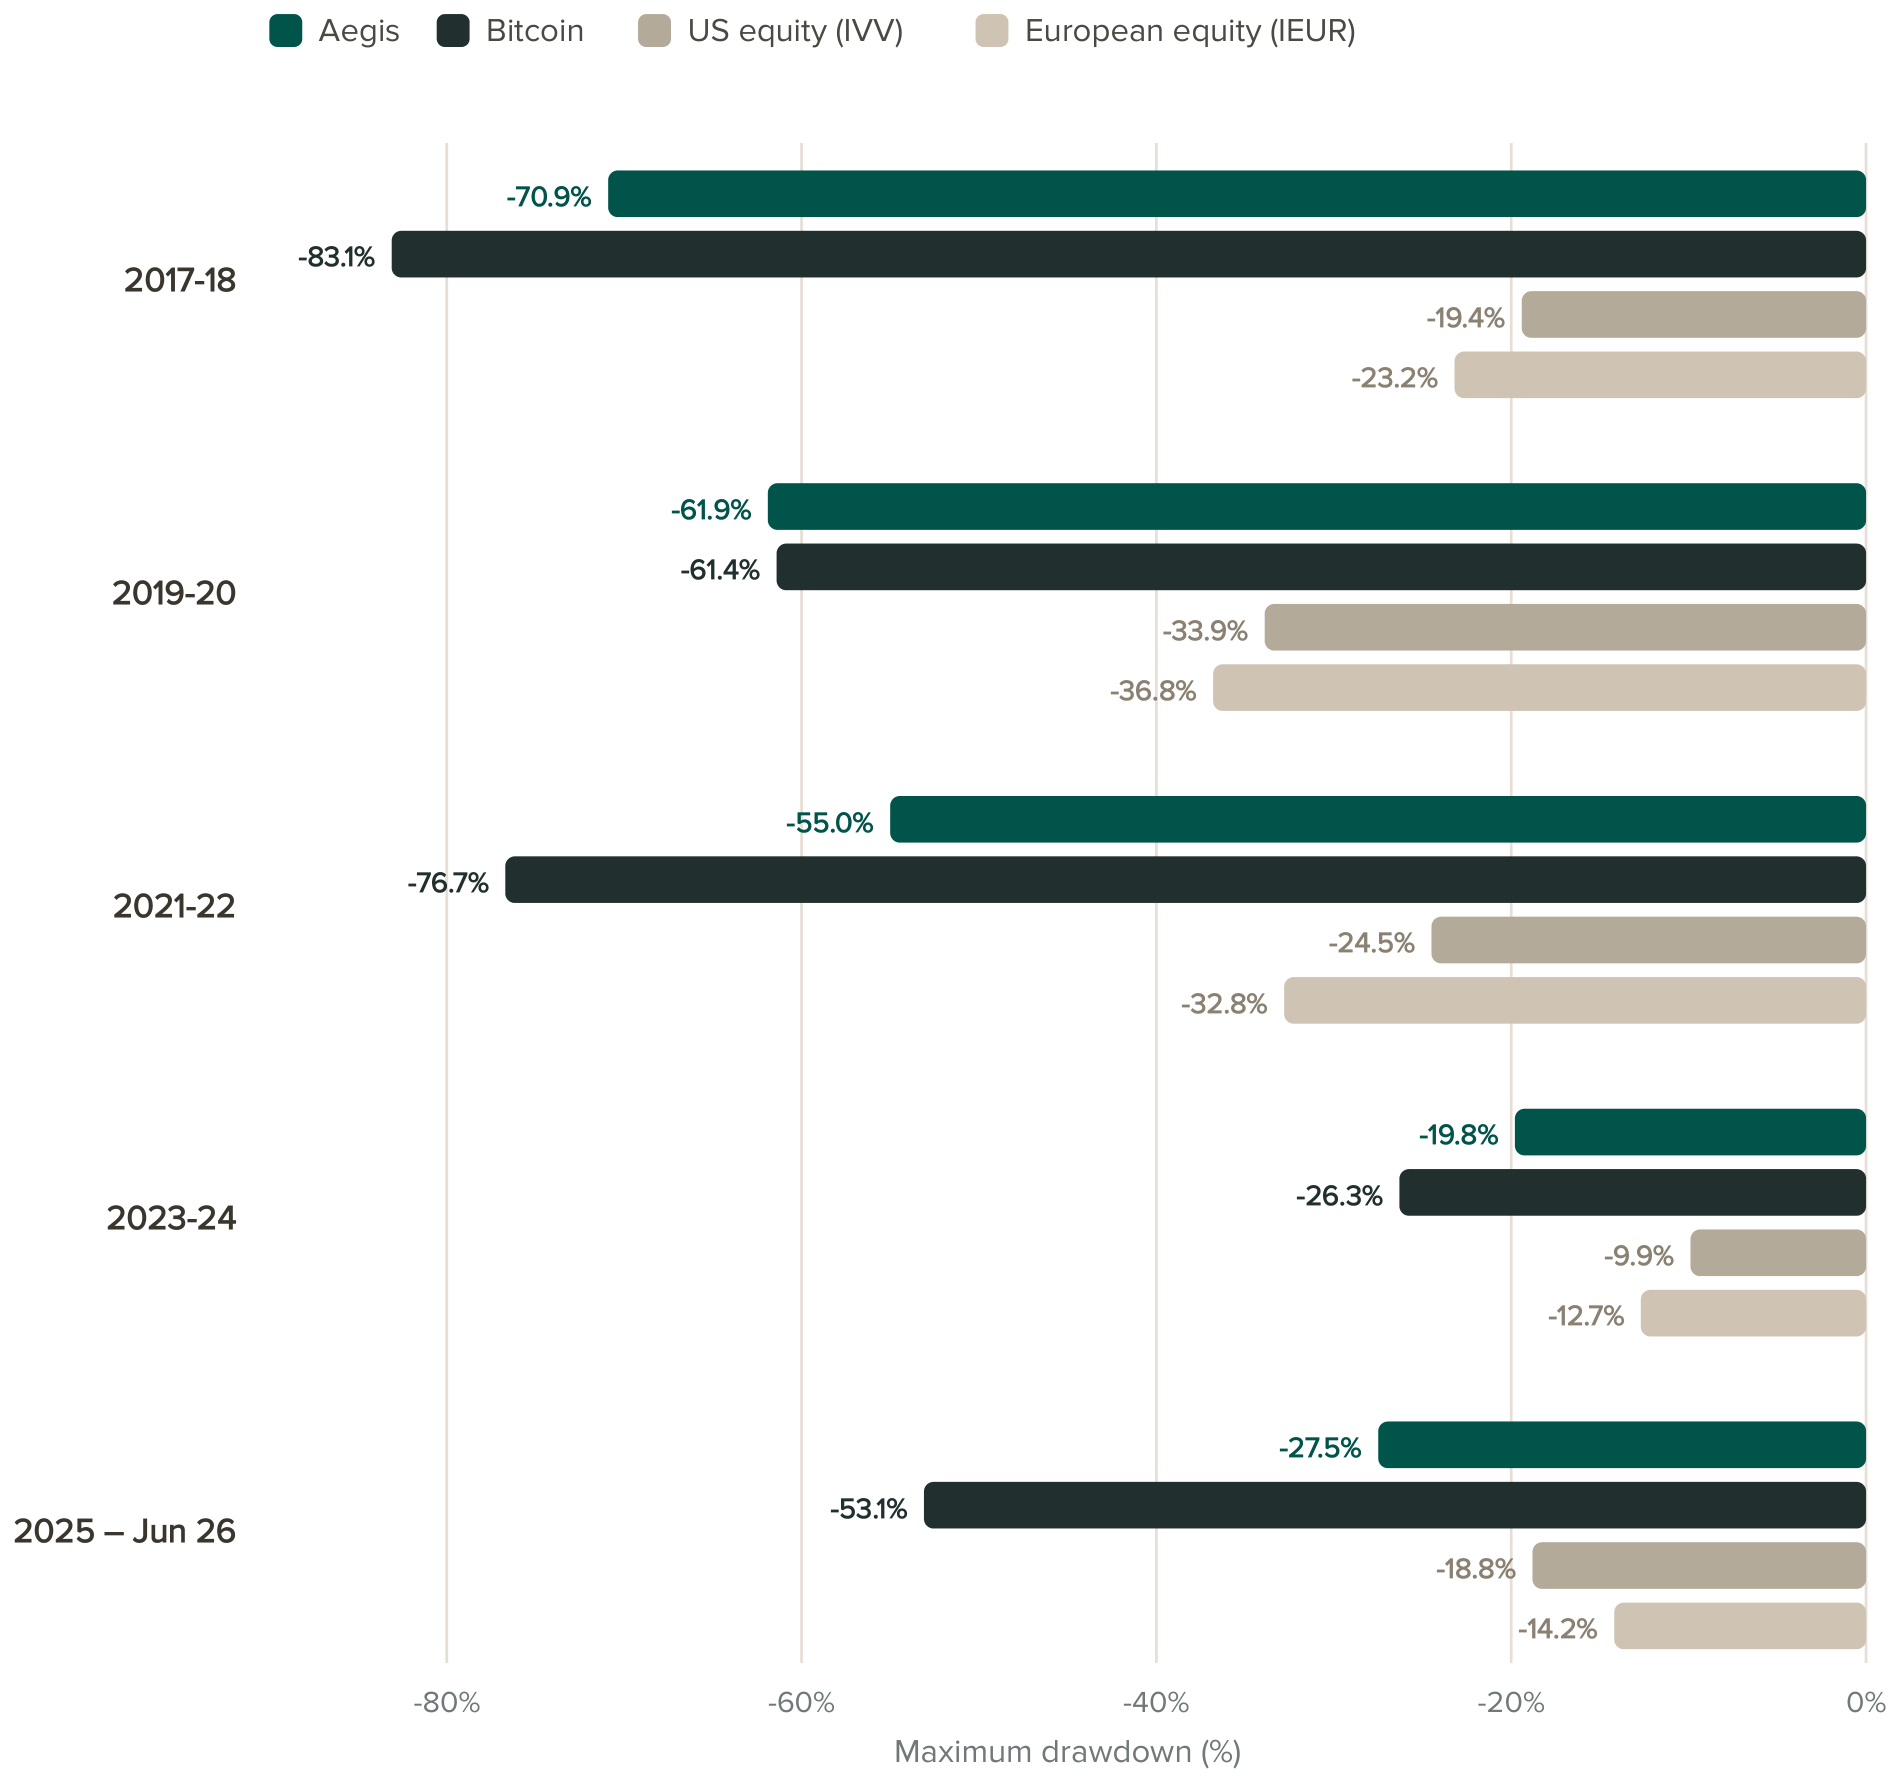
Aegis carries undiminished risk. Its maximum drawdown over the full period was −70.9%. That is shallower than the −83.1% of a direct bitcoin holding, but it remains the second deepest fall in the entire panel. In each of the five sub-periods examined, both Aegis and bitcoin fell further than US equity and European equity.
The most recent period is the weakest. From January 2025 to June 2026 Aegis returned −22.9% cumulatively, at a maximum drawdown of −27.5% and a negative Sharpe ratio of −0.93. Bitcoin lost more over the same period, at −37.3% with a drawdown of −53.1%, yet recorded a higher Sharpe ratio of −0.63. The reason is that the Sharpe ratio does not rank holdings correctly when excess returns are negative: the ratio improves as volatility rises. That period is therefore assessed on return and drawdown rather than on Sharpe.
The full study
The paper also covers the correlation matrices across both samples, the return at each individual stress event, the Sharpe ratio by sub-period, and the full allocation analysis on Sharpe and Sortino, including each base allocation’s peak and the drawdown that comes with it. Methodology, data sources and the derivation of every metric are set out in full.
Getting off zero: from passive to managed exposure. Blockrise Research, August 2026. Study period 1 January 2017 to 30 June 2026, in US dollars, on daily returns.
Investing involves the risk of loss. When investing in crypto assets, you may lose a large part of your entire investment. Past performance of crypto assets does not guarantee future returns. Prices of crypto assets are volatile, which can lead to significant financial losses.
This publication is intended for general information and research purposes only. The information in this publication does not constitute investment advice, advice on crypto assets, legal, tax or other professional advice, and should not be construed as such. Blockrise Capital B.V. does not provide investment advice or advice on crypto assets. Nothing in this publication constitutes a recommendation or invitation to buy, sell or hold bitcoin or other crypto assets, or to make use of any specific investment strategy or financial service.
Blockrise™ is a trademark of Blockrise Capital B.V. in the Netherlands and other countries. Blockrise Capital B.V. is a private limited liability company registered in the Netherlands under Chamber of Commerce number 74879782. Blockrise Capital B.V. holds a MiCAR licence with number 41000029, issued by the Dutch Authority for the Financial Markets (AFM). Blockrise Lending B.V. is a group company of Blockrise Capital B.V. and does not hold a MiCAR licence. Bitcoin-backed loans are not a MiCAR regulated product.
© 2026 Blockrise Capital B.V. All rights reserved.
Learn more
Media

Media
23 Jun
bunq opens banking-as-a-service to industry - with Blockrise as its anchor partner
News
Press release
News
10 Jun
Blockrise sets precedent in the Bitcoin market by reducing custody fees to 0%

No items found
Take control of your Bitcoin. Get started with Blockrise today.
Get started